How to Check Your Credit Score for Free in the UK
Check your Experian, Equifax and TransUnion scores free in minutes. Current 2026 score scales, the soft-search guarantee, and a step-by-step UK guide.
TL;DR: There is no single UK credit score. Experian, Equifax and TransUnion each hold a file on you and each gives you a free way to see it. A free Experian account shows your Experian score, ClearScore shows your Equifax score and report, and Credit Karma shows your TransUnion score and report. Checking your own file is always a soft search, so it never harms your score. Check all three, because lenders do not all report to every agency.
There is no single “UK credit score”. Three separate companies, Experian, Equifax and TransUnion, each hold a file on you, and each calculates its own score on its own scale. The good news: you can see all three for free, and checking your own file never damages your score. When you check your own report it leaves only a soft search, which lenders cannot see.
What is a credit check and how lenders use it
A credit check is what happens when a company reads your credit file. Your file is a running record of your borrowing: accounts you hold, balances, whether payments were on time, missed payments, defaults, County Court Judgments, bankruptcies, who has searched your file, and whether you are on the electoral roll.
Lenders are the most frequent readers, but they are not the only ones. Mobile phone providers check your file when you take a contract (not on pay-as-you-go), energy suppliers may check before offering a fixed tariff, landlords often check prospective tenants, and some employers, mainly in financial services, check as part of pre-employment screening.
When you apply for credit, the lender looks at your file and runs it through its own scorecard alongside affordability checks. That is why the number you see matters less than the data behind it: two people with the same score can get different decisions. Before any application, whether a loan, card or mortgage, checking your own file first is simple common sense. If you are planning a remortgage, read our guide to remortgaging in the UK and the wider Mortgages and Property hub, where knowing your file in advance pays off.
Free credit check: what you get
Every free option below gives you ongoing access at no cost, but “what you get” differs. Some show your score only, some show the full report, and some refresh weekly while others refresh monthly. None of them lets you see exactly what a lender sees, because lenders buy the raw file and apply their own scoring.
| Service | Agency data shown | What is free | Score scale | Updates | Cost |
|---|---|---|---|---|---|
| Free Experian account | Experian | Score; full report in the Experian app | 0 to 1,250 | Weekly | Free |
| MSE Credit Club | TransUnion | Score plus affordability insight and eligibility checker | 0 to 999 (transition from 0 to 710, see below) | Monthly | Free |
| ClearScore | Equifax | Score plus full credit report | 0 to 1,000 | Weekly | Free |
| Credit Karma UK | TransUnion | Score plus full credit report | 0 to 710, moving to 0 to 999 | Weekly | Free |
| Statutory report (direct from each agency) | Experian, Equifax and TransUnion | Complete legal file, no score included | n/a | On request | Free |
How are these services free? ClearScore and Credit Karma earn a commission when someone takes one of the financial offers shown on their site. That is how the model works, and it is the reason the score and report cost you nothing. You never have to take an offer. If you want a fuller picture of borrowing costs when those offers appear, see what APR really costs.
Do not confuse the free Experian account with CreditExpert. CreditExpert is Experian’s paid tier (£14.99 a month after a 30-day trial). The free account is enough for most people. Similarly, note that MSE Credit Club now shows TransUnion data, not Experian data as older guides say: if a page tells you Credit Club is the free route to your Experian file, it is out of date.
Check my credit score: the three free routes
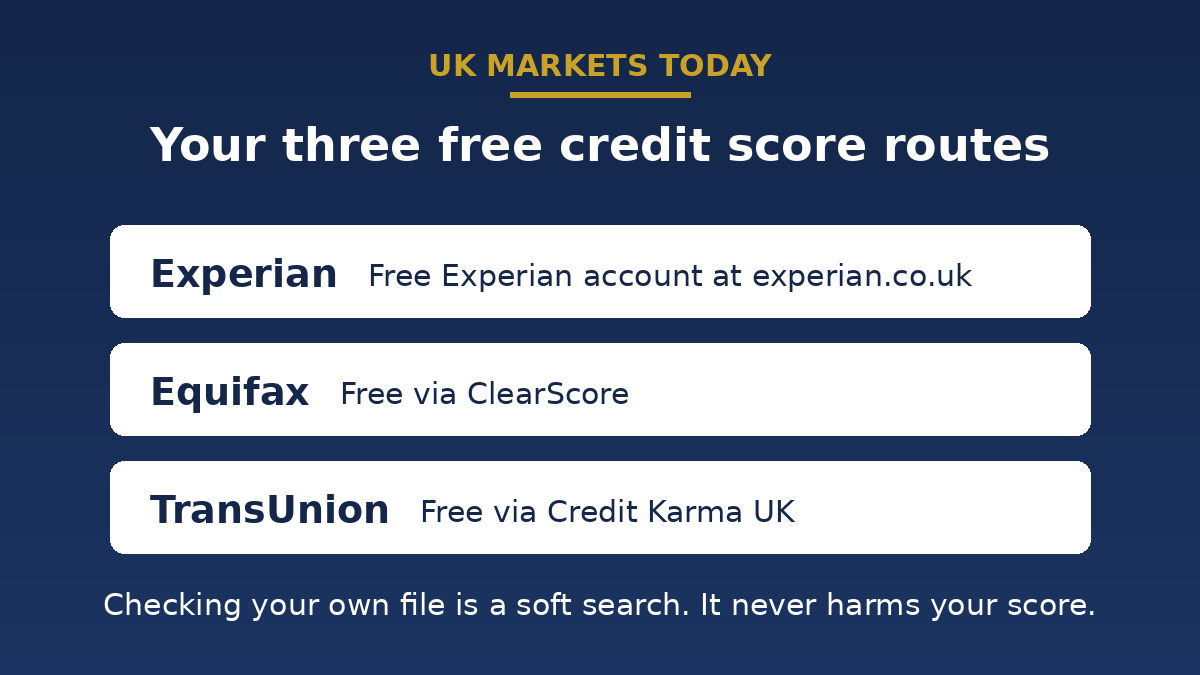
Experian: free Experian account. Sign up at experian.co.uk and you will see your score, updated weekly. The full report is visible in the Experian app. Experian’s scale now runs 0 to 1,250 after the November 2025 overhaul, which also added rental payments, overdraft use and phone contract payments into the scoring model.
Equifax: via ClearScore. ClearScore is free forever and shows the data Equifax holds on you, including your Equifax score and full report, updated weekly. MoneyHelper, the government’s free money-guidance service, recommends checking all three agencies because lenders do not all report to every agency: a missed payment might appear on one file and not another. MoneyHelper’s guide to checking your credit report is the best neutral starting point.
TransUnion: via Credit Karma UK. Credit Karma is free and shows your TransUnion file and score, updated weekly. One caution for 2026: TransUnion is partway through changing its scale from 0 to 710 to 0 to 999, rolling out in phases from late September 2026 to June 2027. You may briefly see two different TransUnion scores depending on where you check. That is normal during the changeover, it does not mean your file changed. For the current bands on all three scales, see what counts as a good credit score in the UK.
How to check credit score: step by step
Every service follows the same rough process, and setting up all three takes about fifteen minutes:
- Pick a service from the table above. If you want all three files, sign up for all three services, each covers one agency.
- Create an account with your name, date of birth and current address, plus previous addresses from the last six years.
- Verify your identity. Expect security questions only you can answer, about past addresses, accounts or credit agreements. Some services may ask for a document check instead.
- View your score and report. Start with the score, then read the report behind it, that is where errors hide.
- Set up alerts. All three free services will email you when your score changes, so check once and let the alerts do the ongoing work.
Statutory reports: the thorough option
By law you can also request your full statutory credit report directly from each agency for free under UK data protection law. It is slower and clunkier than the apps above, but it is the complete legal file, real time, and easy to download, which makes it useful if you are disputing something serious or building an affordability complaint for the Financial Ombudsman.
One thing to know: the statutory report does not include a score. Scores are each agency’s own invention, not something a lender sees, so if you want a quick at-a-glance health check, use the free services above alongside the statutory file.
What to actually look for
- Errors. Accounts you do not recognise, wrong addresses, payments marked late that were not. Errors are common enough that every agency has a dispute process, use it. Also look for searches you do not recognise, which can be an early sign of identity fraud.
- Your electoral roll entry. If you have moved recently and not re-registered to vote, lenders struggle to confirm your identity. Registering to vote is one of the fastest legitimate ways to improve your score.
- Accounts you forgot. Old phone contracts, store cards, unused overdrafts, they all sit on your file. So does buy-now-pay-later borrowing, which became regulated credit on 15 July 2026, meaning it now appears on credit files that lenders read.
- Searches on your file. Your own checks appear as soft searches only you can see. Hard searches from applications stay visible to lenders for twelve months.
Once you have checked, the next step is acting on what you find: our guide on how to improve your credit score covers the ten steps that work. And while you are sorting your finances, you can run the numbers on our calculators, compare cash ISAs with stocks and shares ISAs for your savings buffer, and read how 0% balance transfer cards work if you are carrying card debt. If the balance itself is the worry, our free credit card payoff calculator shows your debt-free date and how much interest a small extra payment each month would save.
Two things checking will not do
It will not lower your score, that is the soft-search point above. You can check every day and it makes no difference. And it will not show you exactly what a lender sees: lenders buy your full file and apply their own scorecards, so a high number on one scale is a guide, not a guarantee. What counts as a “good” score differs by agency, and the scales themselves have just changed, which is worth knowing before you compare old screenshots.
FAQ: checking your credit score in the UK
Does checking my credit score lower it?
No. Checking your own score is always a soft search, which only you can see and which never affects the number. What lenders see are hard searches, recorded when you actually apply for credit. One or two hard searches a year is normal; six or more in twelve months can concern lenders, which is exactly why checking your own file before applying is sensible. Our soft vs hard credit search guide shows which everyday checks are soft and which are hard.
How often should I check my credit score?
At least once a year, and always before a major application such as a mortgage, loan or car finance. Most free services send change alerts, so checking once and leaving alerts on is a fine routine. For background on the numbers you will see, see what counts as a good credit score.
Which free credit score is most accurate?
None is more accurate than the others. Each agency holds slightly different data and runs its own maths on its own scale, so the three numbers will not match. Accuracy is less important than coverage: checking all three files catches errors any single one would miss.
Why are my three scores so different?
Three reasons: different data (not every lender reports to all three agencies), different scales (0 to 1,250, 0 to 1,000 and 0 to 710/999), and different scoring models. During TransUnion’s 2026 scale changeover you may even see two different TransUnion scores, check which scale you are looking at before worrying.
Can I check someone else’s credit score?
No, not without their written permission. You can only access your own file. Joint accounts and financial associations are the exception: a partner’s history on a joint account can appear on your file, which is why it pays to check what financial links you hold.
Is there a completely free way to see my full credit file?
Yes. Beyond the free services above, you have a legal right to your statutory credit report from each of the three agencies at no cost. It is the complete file with no score attached. Keep up with changes that affect your file, such as rate moves and new rules, on UK financial news.
Can I view my credit rating free, or is a rating different from a score?
They amount to the same thing. Credit rating is the older, everyday term, while the agencies call the number a credit score, and MoneyHelper uses both words for the same idea. The free accounts above let you view your rating and get a free credit report behind it, and it is the report, not the number, that lenders actually read.
Why is no score showing when I check my credit score?
No score usually means a thin file: the agency holds little or no borrowing in your name, so there is not enough data to calculate one. It is common if you have never had a credit card, overdraft, loan or contract phone, or if you have recently moved to the UK. Your statutory report still shows whatever is held on you. Registering on the electoral roll at your current address and running a current account in your name give the agencies data to work with, and a score builds as lenders begin reporting your accounts.
How long do defaults and CCJs stay on my credit file?
Six years from the date of the default or the judgment, whether or not you pay the money back, and then they drop off automatically. MoneyHelper confirms the same six-year rule for both defaults and CCJs. Paying still helps: the entry is marked satisfied, which lenders view better than an unpaid mark. One exception is a CCJ paid in full within 30 days of the judgment, which can be removed from the register entirely.
How often does my credit score update?
Whenever new data reaches the agency. Most lenders report your balances and payments once a month, usually around your statement date, and the free services refresh on their own cycles: weekly for the free Experian account, ClearScore and Credit Karma, monthly for MSE Credit Club. So a payment you make today can take up to about a month to show in your score.
What is the difference between a soft search and a hard search?
Checking your own file is always a soft search: only you can see it, and it never affects your score. A hard search is recorded when you apply for credit and stays visible to other lenders for twelve months. Several hard searches in a short period can make lenders cautious. Our soft vs hard credit search guide explains both in full.
Should I check all three agencies?
Yes. Lenders do not all report to every agency, so an error or a missed payment can sit on one file and not the others. It costs nothing: a free Experian account covers Experian, ClearScore shows your Equifax file and Credit Karma shows your TransUnion file.
What information do I need to check my credit rating?
Your full name, your date of birth and your current address, plus previous addresses from the last six years. The service then asks security questions only you should be able to answer, about past addresses, accounts or credit agreements, to prove the file is yours.
What should I do if I find errors in my credit rating report?
Raise a dispute with the agency holding the wrong entry, and check the same detail on your other two files, because an error can sit on one and not the others. Take any account or search you do not recognise seriously: it can be an early sign of identity fraud, and the agency has to investigate disputed entries.
How long does it take to check my credit score?
A few minutes for each service. You create the free account with your personal details and address history, answer the security questions, and your score and report appear straight away. Checking all three agencies takes a few minutes each, so the full set is quick.
Which are the best credit score apps in the UK?
The free ones run by or for the agencies themselves: the Experian app with a free Experian account, ClearScore for your Equifax file, and Credit Karma for your TransUnion file. Each shows your score and report free and refreshes weekly. Anything asking you to pay to see your own score is selling you something the agencies give away.
Checking a business instead of yourself? Company credit reports work differently: Companies House data is free but carries no score, and full company reports are mostly paid. See our guide to checking a company credit report free in the UK.
Last checked: 6 October 2026. Free products change their terms; if a link above asks for payment where we say free, tell us and we will fix it.
Part of our Credit and Financial Health hub.
Got a UK money question?
Ask it in the Ask UKMT live chat. No sign up, no names, and the answers are checked against official sources. Open the live chat